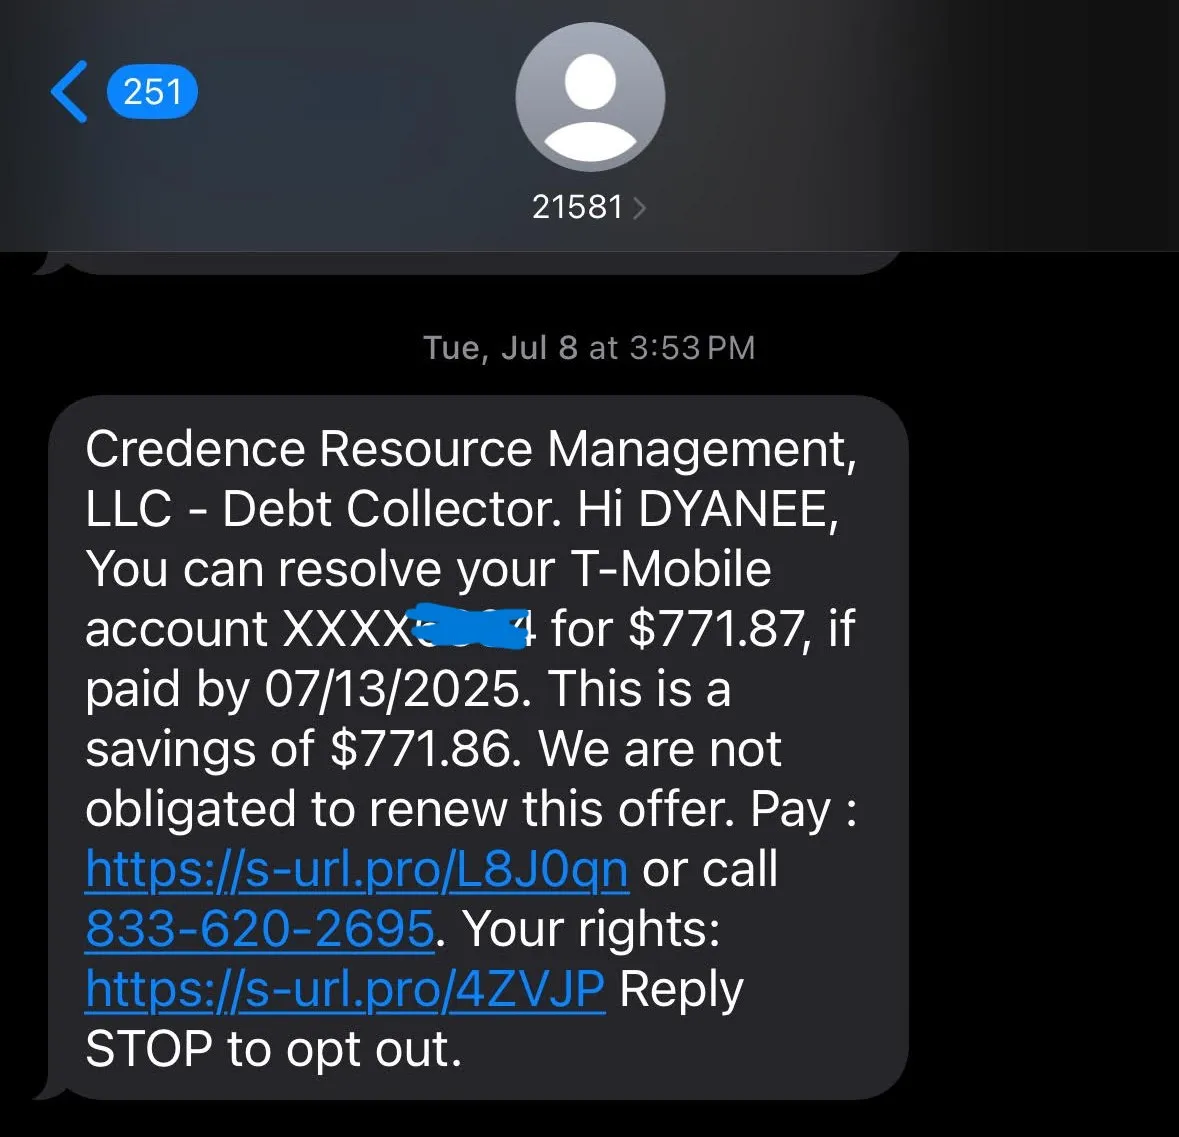
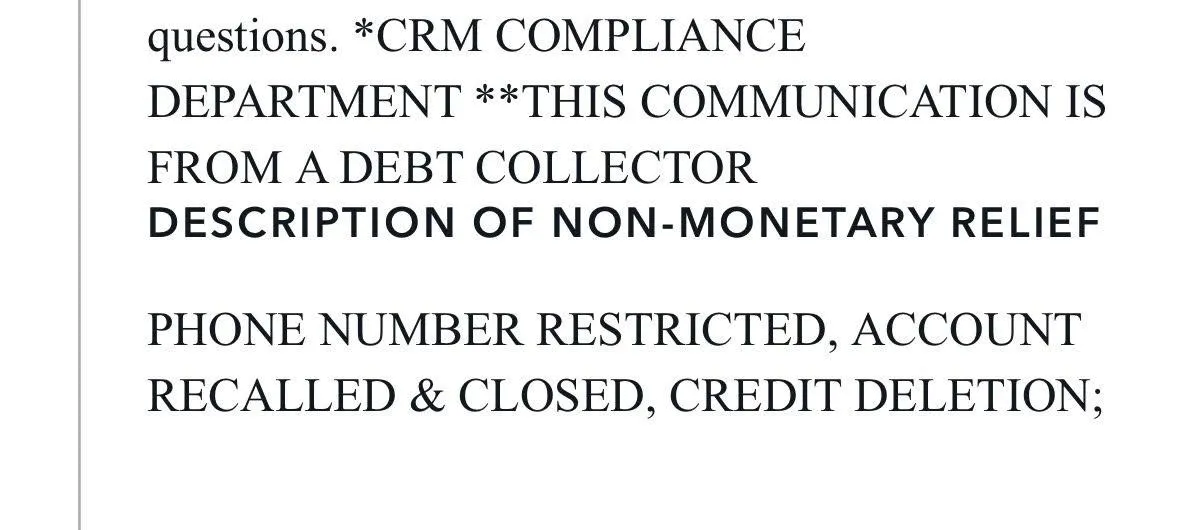
MOST PEOPLE DON’T REALIZE THIS : WHEN A DEBT COLLECTOR SENDS YOU A TEXT MESSAGE, IT MAY RAISE CONSUMER-RIGHTS QUESTIONS.
Did a Debt Collector Text You?
That message may contain more than a demand for payment. It may contain information that helps determine whether your consumer rights were respected under federal and state law.
Potential red flags to look for:
- Texted you without verified prior written consent
- Failed to clearly identify themselves as a debt collector
- Sent automated texts using bulk or robodialing software
- Omitted a clear opt-out mechanism (e.g., 'Reply STOP')
- Contacted you repeatedly, at work, or at irregular hours
What our preliminary review helps evaluate:
- Applicable protections under the FDCPA, FCRA, and TCPA
- Proper documentation steps before you respond or pay
- Next steps and options tailored to your specific situation
🔒 Free preliminary review. No obligation to enroll.
Not every debt-collection message is unlawful. Eligibility depends on the facts, communication records, consent, applicable law, and other circumstances.
CONSUMER EDUCATION
Know My Rights
Understanding federal statutes that regulate debt collection, credit reporting, and automated communications.
FDCPA
Fair Debt Collection Practices Act
Federal law that may protect consumers from certain abusive, deceptive, or unfair debt-collection practices by covered debt collectors.
FCRA
Fair Credit Reporting Act
Federal law that covers consumer reporting and gives rights about the accuracy and handling of information in consumer reports.
TCPA
Telephone Consumer Protection Act
Certain calls and text messages (often involving automated technology) may be regulated depending on consent, technology used, and other facts.
Which law applies depends on the facts. Receiving a debt-collection text does not automatically mean a law was violated.
FREE REVIEW
SEND US THE MESSAGE.
You don’t need to know which law applies. Upload the communication and we’ll review what you provide for potential consumer-rights and credit-reporting issues.
- Prompt, no-cost evaluation by consumer protection advocates
- Assesses TCPA, FDCPA, and Fair Credit Reporting criteria
- Encrypted document storage with strict confidentiality protocols
Privacy & Safety Notice
Please remove unnecessary sensitive information before uploading. Do not upload Social Security numbers, passwords, full bank account numbers, or full payment card numbers.
REAL-LIFE TEXT COMMUNICATIONS
DO ANY OF THESE SOUND
FAMILIAR?
These examples don’t always mean a problem happened, but they might be worth checking out. You can upload the message so we can take a closer look.
"I NEVER GAVE THEM MY NUMBER."
You don’t remember agreeing to get texts about this debt.
"WHO EVEN IS THIS?"
The message might not clearly say who’s contacting you or which account it’s about.
"STOP TEXTING ME."
You asked the sender to stop, but you’re still getting texts.
"THEY WON’T STOP."
You might be getting a lot of messages even after asking them to stop.
"WRONG PERSON."
The sender may be trying to collect a debt for someone else, not you.
"THIS FEELS THREATENING."
The message might use language that feels too urgent, scary, or confusing.
"I DON’T RECOGNIZE THIS DEBT."
They might be asking for money on accounts or fees you don’t remember opening.
"I DISPUTED IT - THEY KEPT CONTACTING ME."
You could have disputed the debt or asked for proof, but the texts didn’t stop.
Some of these situations might raise questions about your rights. Whether that applies depends on the details, the messages, consent, who’s contacting you, the rules, and other factors.
If you’ve ever received a text from a collector - even once - you can upload it for a review.

How does submitting messages help?
If a debt collector contacts you under questionable circumstances — such as without permission, improper identification, or automated messages — there may be applicable federal laws.
We assess these factors to help clarify what they could mean for you.
What happens after I submit my information?
You’ll receive:
A secure client portal to upload your reports and communications.
A detailed FCRA/FDCPA/TCPA review within 48-72 hours.
A summary explaining possible next steps based on your information.
We then provide guidance to help you understand your options.
Which laws may apply to my situation?
You’re protected by several laws:
FDCPA (Fair Debt Collection Practices Act) - Regulates how collectors contact you
FCRA (Fair Credit Reporting Act) - Controls what can legally be reported
TCPA (Telephone Consumer Protection Act) - Protects you from unauthorized calls and texts
We review your communications under these laws to help explain any potential issues and options.
What can I expect from this review?
Each situation is unique, so we do not guarantee outcomes.
Our role is to thoroughly review your evidence and guide you on possible next steps.
What if I never got a text - can I still submit my info?
Yes!
Texts are just one form of communication that may raise concerns.
If you’ve received calls, letters, duplicate reporting, balance errors, or unverifiable data, we can still review your information.
Do I need to provide proof of any issue?
No - I handle that for you.
You’ll simply forward any texts, letters, or call logs, and we’ll review them to identify potential consumer-rights and credit-reporting issues.